FIELD GUIDE 01 · RENTAL ACQUISITION
Build your investment Criteria before the listing changes the rules.
A property should not pass or fail in the abstract. It should be screened against rules that reflect what the investor is trying to accomplish, what the investor cannot risk, and what still needs evidence.
01 / DEFINE THE INVESTMENT JOB
Start with the decision the property must support.
“Find a good deal” is too vague to screen consistently.
Name the primary job first: durable current cash flow, a learning-sized first acquisition, lower operating complexity, a specific portfolio role, or another explicit objective. Then name what the property is not expected to do. A clear job prevents unrelated upside stories from becoming accidental justification.
If this property performs exactly as modeled—but never gets easier, rents never jump, and appreciation is unknown—does it still do the job?
02 / SET HARD CONSTRAINTS
Decide which boundaries are allowed to end the screen.
Hard constraints should be few, explicit, and observable. If a rule can always be waived when the listing is exciting, it is not functioning as a constraint.
03 / CHOOSE FINANCIAL RULES
Use thresholds to expose tradeoffs—not manufacture certainty.
| Rule type | Question it answers | Common failure |
|---|---|---|
| Capital required | Can this acquisition be completed within the available capital envelope? | Ignoring closing costs or immediate work |
| Post-close reserves | How much liquidity remains after the modeled acquisition? | Treating unused credit as cash reserves |
| Monthly cash flow | Does modeled income cover operating costs, reserves, management, and debt? | Leaving out costs because they are not billed monthly |
| Debt-service coverage | How much modeled operating income covers modeled debt service? | Using an unstated income or expense basis |
| Cash-on-cash return | What modeled annual cash flow is produced by modeled cash invested? | Comparing results built from different capital definitions |
A threshold should identify what needs to change or be verified. It does not turn incomplete inputs into a recommendation.
04 / DEFINE THE EVIDENCE STANDARD
Do not let an estimate quietly become a fact.
A lease, tax record, insurance quote, inspection finding, or another reviewable source.
Useful context derived from imperfect evidence and kept visibly provisional.
An investor-controlled planning input that can be changed without rewriting the source evidence.
A gap that remains open until evidence is found; unknown should not silently become zero.
CRITERIA IN THE PRODUCT
Criteria become more useful when they survive the calculation.
DealLens keeps the saved rules next to potential matches and the resulting Financial Screen. The interface shown here uses synthetic demonstration properties—not live inventory.
Open the full product capture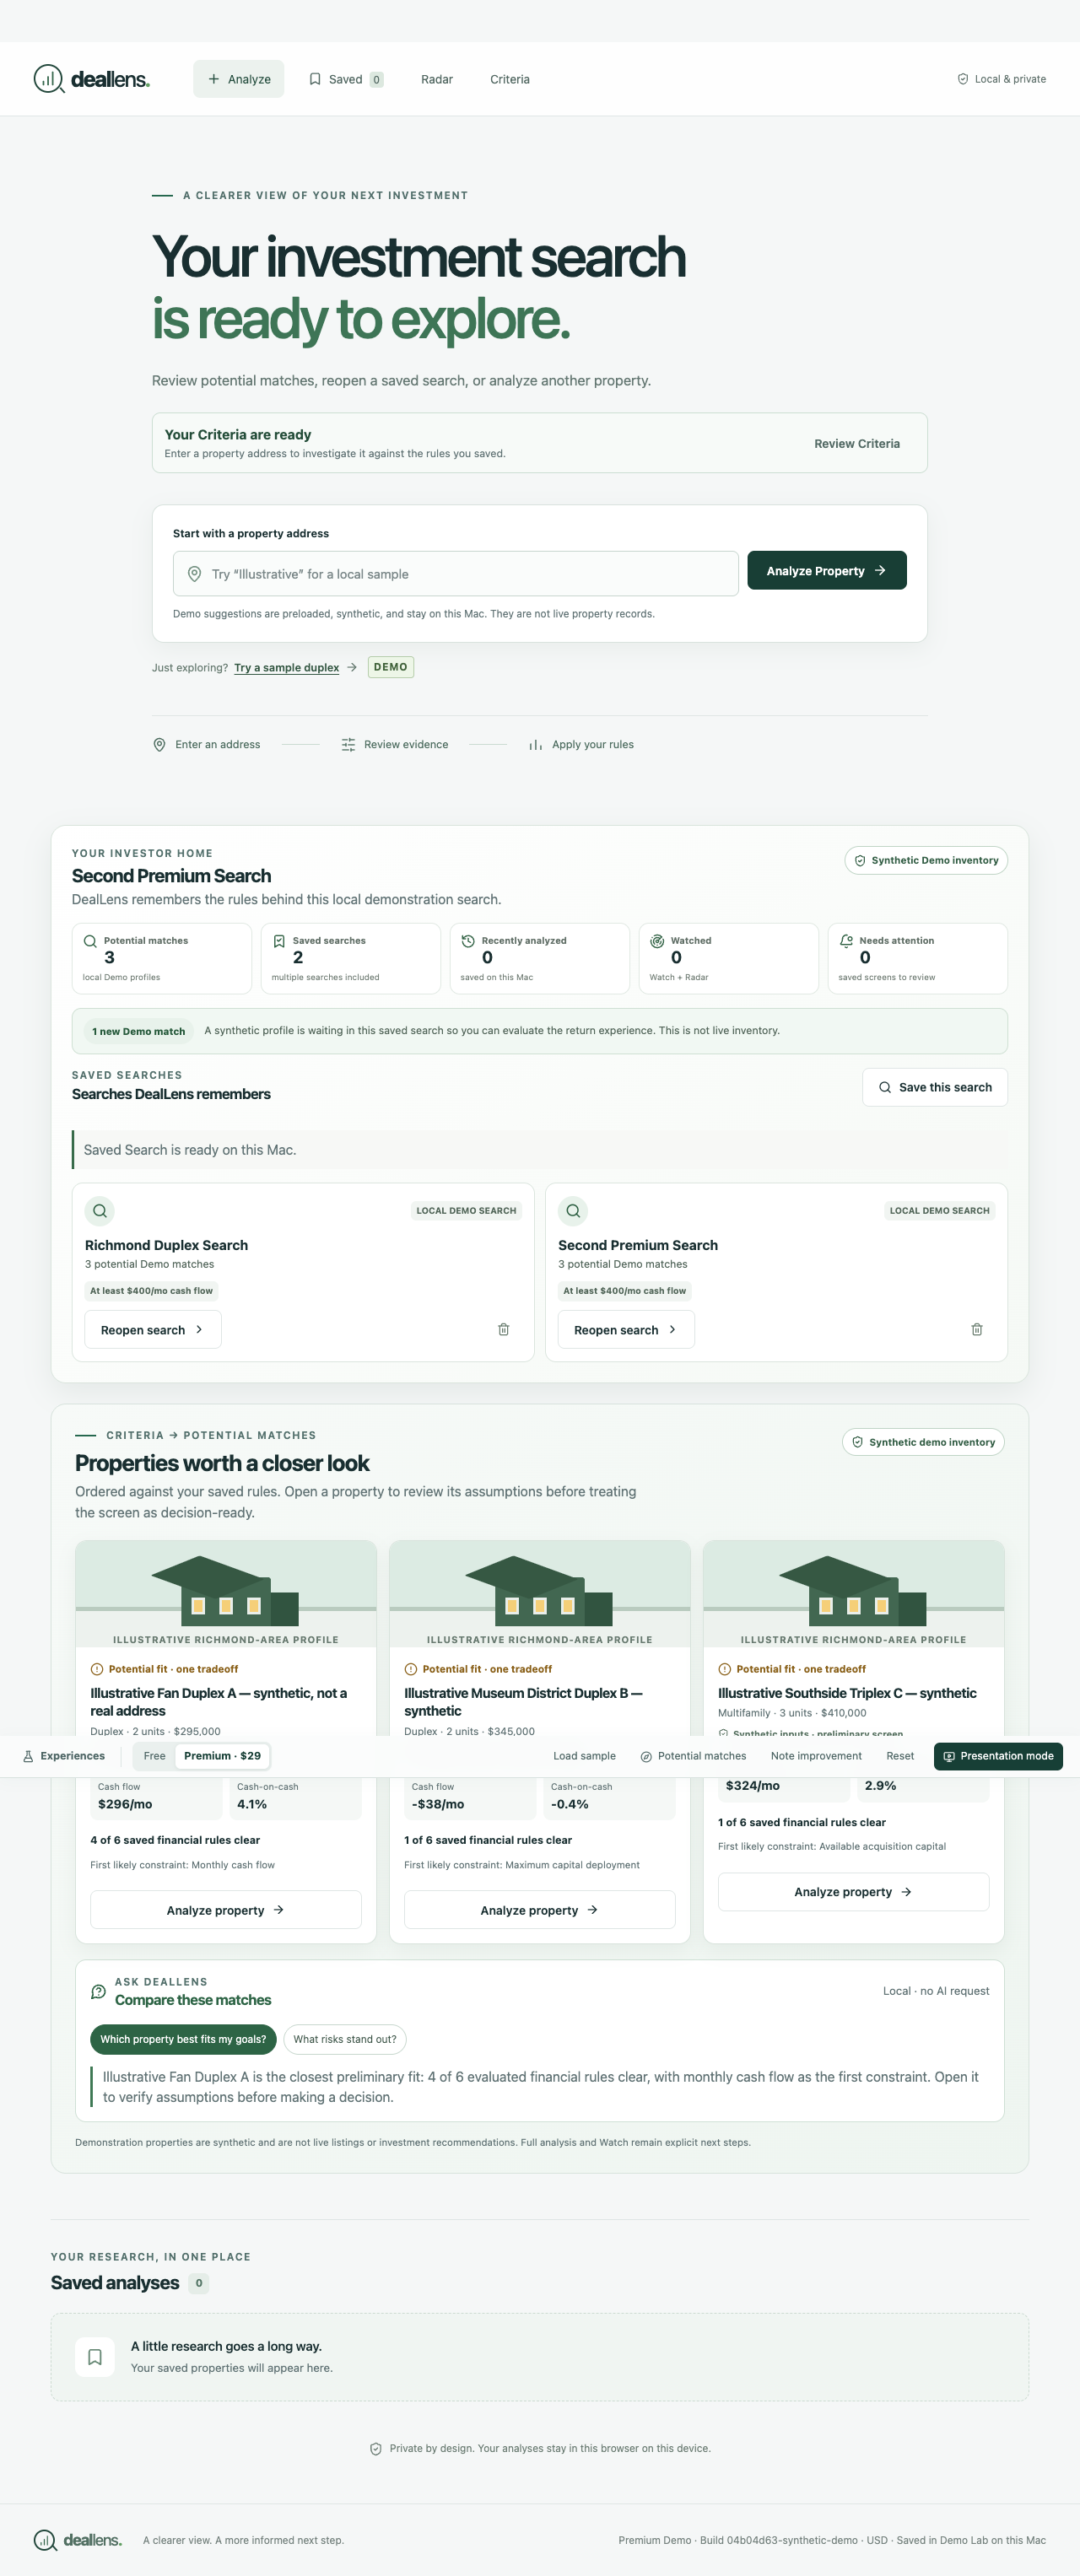
05 / USE THE RULES IN ORDER
Turn Criteria into a repeatable first screen.
- Record property identity and source evidence.Keep listing statements, public facts, estimates, and investor inputs distinguishable.
- Apply hard constraints first.A property that cannot fit the mandate does not need optimistic fine-tuning.
- Run the financial screen.Use one visible set of financing, income, expense, reserve, and capital assumptions.
- Name the first material constraint.Start the next question where the investor’s rules first stop clearing.
- Change one input at a time.Use sensitivity to learn what drives the result instead of stacking favorable changes.
- Write the diligence plan.A clear initial screen identifies what deserves verification; it does not replace verification.
- Preserve the decision.Save the evidence, assumptions, rules, result, and open questions used at that moment.
06 / CRITERIA WORKSHEET
Write a one-page mandate before screening the next property.
What must this property contribute to the portfolio?
Which geography, property type, unit shape, condition, and complexity fit?
What is the maximum deployment, and what liquidity must remain?
Which modeled cash flow, coverage, return, or other thresholds matter—and why?
Which facts must be documented before the first screen can clear?
Which lease, physical, insurance, title, zoning, financing, and operating questions always remain?
Keep the first version short. A mandate that cannot be remembered or applied consistently is too complicated for a first screen.